
Perth Home Loan Process: Complete Step-by-Step Guide 2026
Buying a property is a major financial commitment. Understanding the home loan process Perth helps you prepare for each stage, from reviewing your finances to getting approval and completing settlement.
The home loan process in Australia involves comparing lenders, preparing documents, applying for pre-approval, and meeting the lender’s requirements. Knowing what to expect can help you make informed decisions and avoid unnecessary delays.
At Lime Mortgage Brokers, we help borrowers in Kinross and surrounding Perth suburbs understand their home loan options and navigate the application process.
Table of Contents
What Is the Home Loan Process in Australia?
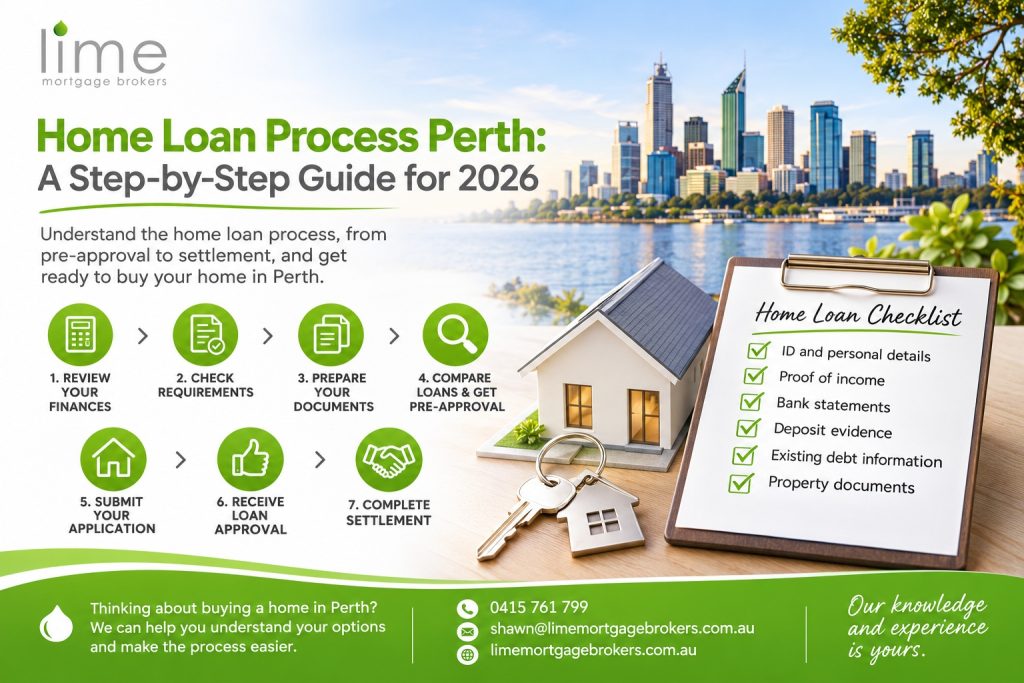
The home loan process is the series of steps involved in obtaining finance to purchase a property. Although requirements vary between lenders, the process generally includes:
- Assessing your finances and borrowing capacity.
- Comparing home loan options.
- Preparing the required documents.
- Applying for pre-approval.
- Finding a property.
- Submitting a formal application.
- Receiving loan approval.
- Completing settlement.
Understanding these stages before applying for a home loan can help you plan your budget and prepare for the requirements involved.
Step 1: Review Your Finances
Before applying for a home loan, review your income, savings, living expenses, and existing debts. These factors help determine how much you can borrow and whether the repayments fit your budget.
Lenders generally assess your employment, income, credit history, deposit, and financial commitments. They may also consider credit card limits and other loans when calculating your borrowing capacity.
Remember to budget for additional costs, including stamp duty where applicable, conveyancing fees, insurance, inspections, and ongoing property maintenance.
For Perth buyers, comparing property prices across suburbs can help you set a realistic budget before you start your search.
Before choosing a loan, explore available home loan options to understand the products and features that suit your financial circumstances. Comparing your options early can help you make a more informed decision before submitting an application.
Step 2: Understand Home Loan Requirements in Australia
Home loan requirements in Australia vary by lender, your financial circumstances, and the property you plan to buy.
Lenders generally consider your income, employment stability, living expenses, existing debts, credit history, and deposit. They also assess whether you can afford the proposed repayments.
Your deposit affects your loan-to-value ratio (LVR), which compares the amount borrowed with the property’s assessed value. A smaller deposit may result in additional requirements, such as lenders’ mortgage insurance, depending on your circumstances and the loan.
Eligible buyers may also access government-supported home-buying schemes, subject to current eligibility rules.
Meeting the general home loan requirements does not guarantee approval. Each lender assesses applications according to its own policies.
Step 3: Prepare the Documents Needed for a Home Loan
Gathering the required documents early can help prevent delays during the application process.
Common documents include:
- Identification: A passport, driver’s licence, or other accepted identification.
- Proof of income: Recent payslips and employment details for employees.
- Bank statements: Records showing savings, income deposits, and regular expenses.
- Deposit evidence: Documents confirming your available savings or other acceptable deposit sources.
- Debt information: Details of credit cards, personal loans, car finance, and other commitments.
- Tax returns and financial statements: These may be required for self-employed applicants.
- Property documents: Details of the property and purchase contract once you have selected a home.
The exact documents required depend on your circumstances and the lender’s policies. Accurate, up-to-date records can make applying for a home loan easier.
Step 4: Compare Loans and Apply for Pre-Approval
Before choosing a lender, compare interest rates, fees, repayment options, and loan features. Consider whether a fixed, variable, or split interest rate suits your needs.
You should also review the comparison rate and consider features such as offset accounts and redraw facilities. The cheapest advertised rate isn’t always the best option once you factor in fees and conditions.
Pre-approval provides an indication of how much a lender may be willing to lend, subject to further assessment and conditions. It can help you set a realistic property budget before making an offer.
However, pre-approval is not a guarantee of finance. The lender must still assess your chosen property and complete the formal approval process.
Read our guide on how to get home loan pre-approval to understand the information lenders may request, how pre-approval works, and what to expect before you begin searching for a property.
Step 5: Submit Your Home Loan Application
Once you have selected a property and entered into a purchase contract, you can submit your formal home loan application.
The lender will review your financial information, verify your income and expenses, and assess the property. It may request updated payslips, bank statements, or additional documents.
Respond promptly to requests and inform your broker about significant changes to your employment or financial circumstances. New debts or income changes may affect the lender’s assessment.
Before committing to a purchase, understand your contract deadlines and consider seeking guidance from your conveyancer or settlement agent about finance conditions.
Getting Buy Ready in Perth
Preparing your finances before you start looking for a property can help you approach the home buying process with greater confidence.
Checking your credit file, managing your bank accounts and debts, setting a budget, maintaining consistent employment where possible and avoiding unnecessary personal debt can all help you prepare for your application.
It is also important to remember that every lender has its own lending policies. Your borrowing capacity and eligibility will depend on your individual financial circumstances and the lender’s assessment.
Step 6: How Does the Home Loan Approval Process Work?
The home loan approval process involves assessing whether your application meets the lender’s lending criteria.
The lender typically reviews your income, expenses, employment, credit history, deposit, and the property’s value. It may request further information before making a decision.
Some borrowers receive conditional approval while they complete outstanding requirements. Formal approval generally follows once the lender has completed its checks and is satisfied that the necessary conditions have been met.
If the property valuation is lower than the purchase price, the lender may offer a smaller loan than expected. You might need a larger deposit or need to reconsider your options.
Providing complete and accurate information can help reduce avoidable delays, although approval is never guaranteed.
Step 7: Complete Settlement
After formal approval, your lender prepares the required loan documentation. Your conveyancer or settlement agent coordinates the legal and financial steps needed to complete the purchase.
You may need to sign documents, arrange insurance where required, provide the remaining purchase funds, and confirm settlement arrangements.
Once settlement is complete, ownership transfers through the relevant property transfer process, and your home loan repayments begin under the loan agreement.
Review your repayment schedule, interest rate, and loan features so you understand your ongoing commitments.
How Long Does the Home Loan Process Take?
The time required depends on the lender, application complexity, and availability of supporting documents.
Pre-approval may take a few business days, while formal approval can take several days to a few weeks. Additional checks or incomplete documentation may extend these timeframes.
Settlement often occurs within the period specified in the purchase contract. In many transactions, this is around 30 to 90 days, although the agreed timeframe can differ.
Preparing documents early and responding promptly to lender requests can help keep the process moving.
Contact Lime Mortgage Brokers
Understanding the home loan process Perth can help you prepare for each stage of purchasing a property. Lime Mortgage Brokers can help you explore available loan options and understand the application requirements.
Contact Lime Mortgage Brokers to discuss your circumstances and property goals.
Shawn Swart
t. 0415 761 799
e. shawn@limemortgagebrokers.com.au
w. www.limemortgagebrokers.com.au
Disclaimer
The information contained on the Lime Mortgage Brokers website and in its posts is for general information purposes only. Lime Mortgage Brokers assumes no responsibility for errors or omissions in the contents of this publication. The information we provide may not be relevant for all individual circumstances. You should always seek professional advice before taking action in relation to any of the matters discussed in this publication.
Frequently Asked Questions
What Is the Process of Home Loan Approval?
The lender assesses your income, expenses, employment, credit history, deposit, and property details. If your application meets the criteria and you meet all requirements, the lender may approve your loan.
How Many Days Does the Home Loan Process Take?
Pre-approval may take a few business days, while formal approval can take several days to a few weeks. The overall purchase process also includes settlement, depending on your contract.
What Do I Need for a Home Loan Application?
You generally need identification, proof of income, bank statements, evidence of savings, and details of existing debts. Self-employed applicants may also need tax returns and financial statements.
How Long Does Home Loan Approval Take?
Approval timeframes vary between lenders. Complete documentation and prompt responses to requests may help prevent unnecessary delays.
How Does the Home Loan Process Work?
You review your finances, compare loans, obtain pre-approval, select a property, submit your formal application, receive approval, and complete settlement.