
Mortgage Stress in Australia: Warning Signs and Ways to Take Back Control
Keeping up with mortgage repayments can become challenging as interest rates, household bills, and everyday living costs rise. For Australian homeowners, these expenses can leave less money available for essential needs and unexpected costs.
Mortgage stress in Australia can affect homeowners at different stages of their homeownership journey. Whether you are experiencing mortgage stress in Perth WA or elsewhere in the country, recognising the warning signs early can help you review your finances and explore possible solutions.
At Lime Mortgage Brokers, we help Perth homeowners explore home loan options that suit their financial circumstances. Understanding your current loan, reviewing your budget, and seeking support when needed can help you take practical steps to manage mortgage stress and regain control.
Table of Contents
What Is the Mortgage Stress Definition in Australia?
In Australia, mortgage stress generally refers to a situation where a household struggles to manage mortgage repayments alongside essential living expenses.
A commonly used indicator is when a household spends more than 30% of its gross income on housing costs, particularly among lower-income households. However, this is a general guideline, not a universal definition. A household spending less than 30% may still experience financial pressure if it has high living expenses, other debts or limited savings.
For example, a household earning $8,000 per month before tax and paying $2,800 towards its mortgage spends 35% of its gross income on repayments. Whether this represents mortgage stress also depends on the household’s other expenses and financial commitments.
Understanding your overall budget is more useful than relying on a percentage alone.
What Are the Common Mortgage Stress Warning Signs?
Mortgage stress warning signs can develop gradually, making them easy to overlook. Recognising these changes can help you decide when to review your finances.
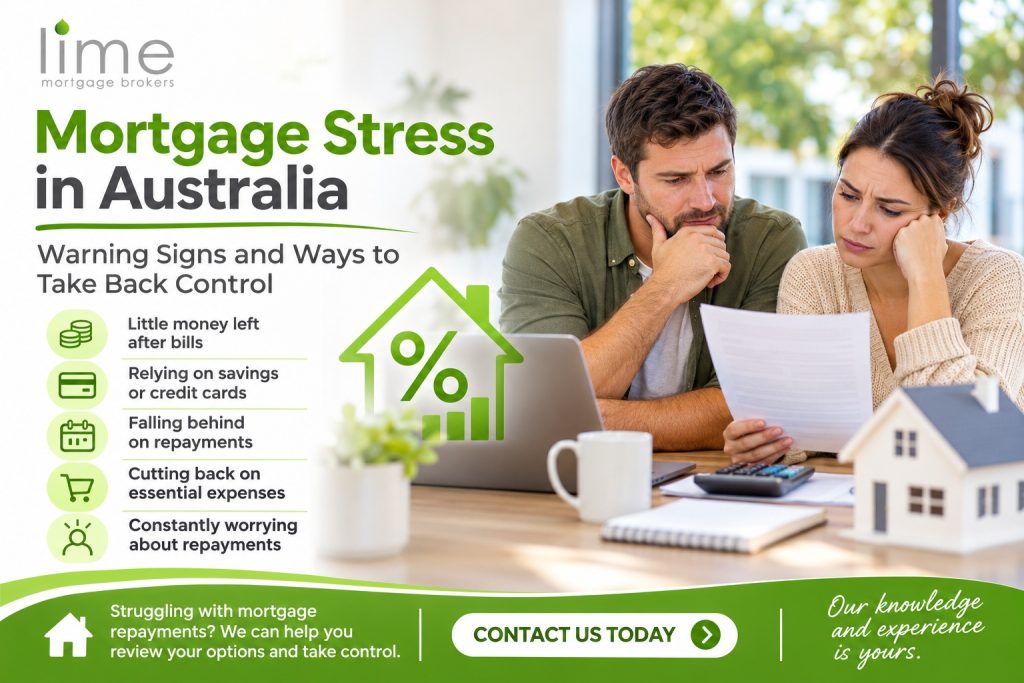
1. Having little money left after bills
If most of your income goes towards your mortgage, utilities, groceries, and other essential expenses, you may struggle to cover unexpected costs or save for the future.
2. Relying on savings or credit cards
Using savings for everyday expenses or relying on credit cards for necessities can make your budget hard to manage.
3. Falling behind on repayments
Missing mortgage repayments or delaying other bills can signal growing financial pressure. Contact your lender early if you think you may have trouble making a payment.
4. Cutting back on essential expenses
If you regularly cut back on food, healthcare, or transport to afford your mortgage, it may be time to reassess your financial position.
5. Constantly worrying about repayments
Financial pressure can affect your sleep, concentration and general wellbeing. If you are frequently worried about upcoming repayments, reviewing your budget and seeking support may help.
For additional guidance, read our article on how to manage mortgage stress.
What Percentage of Income Is Considered Mortgage Stress?
The mortgage stress percentage of income is often assessed using the 30% benchmark. This means that when housing costs exceed 30% of gross household income, many measures consider the household at risk of housing stress.
For example, if your household earns $10,000 per month before tax and your mortgage repayment is $3,000, your repayment represents 30% of your gross income.
However, this calculation does not tell the whole story. A household with substantial childcare costs, personal loans or other financial commitments may struggle even below this threshold. Meanwhile, another household with a higher income may manage a similar repayment percentage more comfortably.
When assessing your financial position, consider your income, essential expenses, other debts, and available savings together.
Is Having a Mortgage Stressful?
Having a mortgage is not automatically stressful. Many homeowners manage their repayments comfortably when their loan suits their income and financial circumstances.
However, rising interest rates, higher living costs, reduced working hours or unexpected expenses can make repayments harder to afford. The pressure can be greater when a household has little emergency savings or several other financial commitments.
If your mortgage is becoming difficult to manage, reviewing your budget and existing home loan may help you identify possible next steps.
Why Is Getting a Mortgage So Stressful?
Applying for a mortgage can feel stressful because lenders assess several aspects of your financial situation, including income, living expenses, credit history, existing debts, and your ability to afford repayments.
The application process may also involve gathering documents, comparing loan products and meeting lender requirements.
What Can Disqualify You From a Mortgage?
A lender may decline a mortgage application if it does not meet its lending criteria. Potential reasons include insufficient income, high existing debts, credit history concerns, an inadequate deposit or equity position, and incomplete documentation.
Each lender has different requirements, so an unsuccessful application with one lender does not necessarily mean every lender will reach the same decision. A mortgage broker can help you understand lending criteria and explore options that may suit your circumstances.
How to Take Back Control of Mortgage Stress
If you are struggling to pay your mortgage, acting early can help you understand your options.
Review your household budget
List your income, mortgage repayments, bills, groceries, transport costs and other financial commitments. Identify expenses you may be able to reduce without affecting essential needs.
Contact your lender
If you anticipate difficulty making repayments, contact your lender as soon as possible. Explain your circumstances and ask about financial hardship home loan assistance. Depending on your situation, your lender may discuss temporary repayment arrangements or other support.
Review your existing home loan
Check your current interest rate, fees, loan features and repayment arrangements. Comparing these details with other available options may help you determine whether your current loan remains suitable.
Explore the home loan options available through Lime Mortgage Brokers to understand different loan types and choose the one that best suits your circumstances.
Consider debt consolidation
If you manage credit cards, personal loans, or other debts alongside your mortgage, these repayments may add to your financial pressure. Debt consolidation may let you combine eligible debts into one loan, potentially simplifying repayments.
However, compare interest rates, fees, and the total amount payable before you decide. Extending debts over a longer loan term may increase the total interest you pay. Learn more about debt consolidation options with Lime Mortgage Brokers.
Build savings where possible
If your budget allows, setting aside a small amount regularly can help you prepare for unexpected expenses. Start with an achievable amount and increase it when your circumstances permit.
Can Refinancing Help Reduce Mortgage Stress?
Refinancing involves replacing your existing home loan with another loan, either with your current lender or a different provider. Depending on your circumstances, refinancing may provide access to a different interest rate, loan structure or features.
However, refinancing is not guaranteed to reduce your repayments or overall borrowing costs. Consider application fees, ongoing charges, loan terms and eligibility requirements before deciding. Extending your loan term may lower regular repayments but increase the total interest paid.
If your income has fallen or you have missed repayments, qualifying for a new loan may be more difficult. Contact your current lender to discuss hardship assistance before assuming that refinancing is the best option.
Finding Mortgage Stress Support in Perth WA
Homeowners experiencing mortgage stress in Perth WA may benefit from different types of support, depending on their financial circumstances.
Your lender can explain its hardship assistance process and discuss whether support is available. A mortgage broker in Perth can help you review your existing home loan and understand potential lending options.
If you need help managing debts or household expenses, the National Debt Helpline provides free financial counselling in Australia. Call 1800 007 007 to discuss your circumstances and available support.
Seeking help early can give you more time to understand your options before financial pressure becomes harder to manage.
Contact Lime Mortgage Brokers Today
Mortgage stress can feel overwhelming when repayments and everyday expenses leave little room in your budget. Recognising the warning signs, reviewing your finances and seeking support early can help you take practical steps towards greater financial control.
If you are concerned about your home loan repayments, contact Lime Mortgage Brokers to discuss your circumstances and explore the home loan options that may be available to you.
Shawn Swart
t. 0415 761 799
e. shawn@limemortgagebrokers.com.au
w. www.limemortgagebrokers.com.au
Disclaimer
The information contained on the Lime Mortgage Brokers website and in its posts is for general information purposes only. Lime Mortgage Brokers assumes no responsibility for errors or omissions in the contents of this publication. The information we provide may not be relevant for all individual circumstances. You should always seek professional advice before taking action in relation to any of the matters discussed in this publication.
Frequently Asked Questions
What Is Considered Mortgage Stress in Australia?
Mortgage stress generally describes difficulty managing mortgage repayments alongside essential living expenses. Spending more than 30% of gross income on housing costs is a common indicator, but it isn’t a definitive measure for every household.
What Are the Common Warning Signs of Mortgage Stress for Australian Homeowners?
Warning signs include having little money left after bills, relying on credit cards for everyday expenses, using savings regularly, falling behind on repayments, and cutting back on essentials.
How Can I Check If I’m at Risk of Mortgage Stress Using Online Tools?
Mortgage repayment calculators can help you estimate repayments and see how interest rate changes may affect your budget. Budgeting tools can also help you compare income with expenses. These tools provide estimates and cannot fully assess your financial circumstances.
What Are the Best Services to Help Manage Mortgage Stress in Australia?
Your lender may offer financial hardship assistance if you are struggling with repayments. A mortgage broker can help you review suitable home loan options, while the National Debt Helpline provides free financial counselling on 1800 007 007.
Can a Mortgage Broker Help If I Am Struggling to Pay My Mortgage?
A mortgage broker can help you understand your home loan options and assess whether refinancing suits your circumstances. If you are experiencing financial hardship, it may also be important to contact your lender and seek financial counselling.