
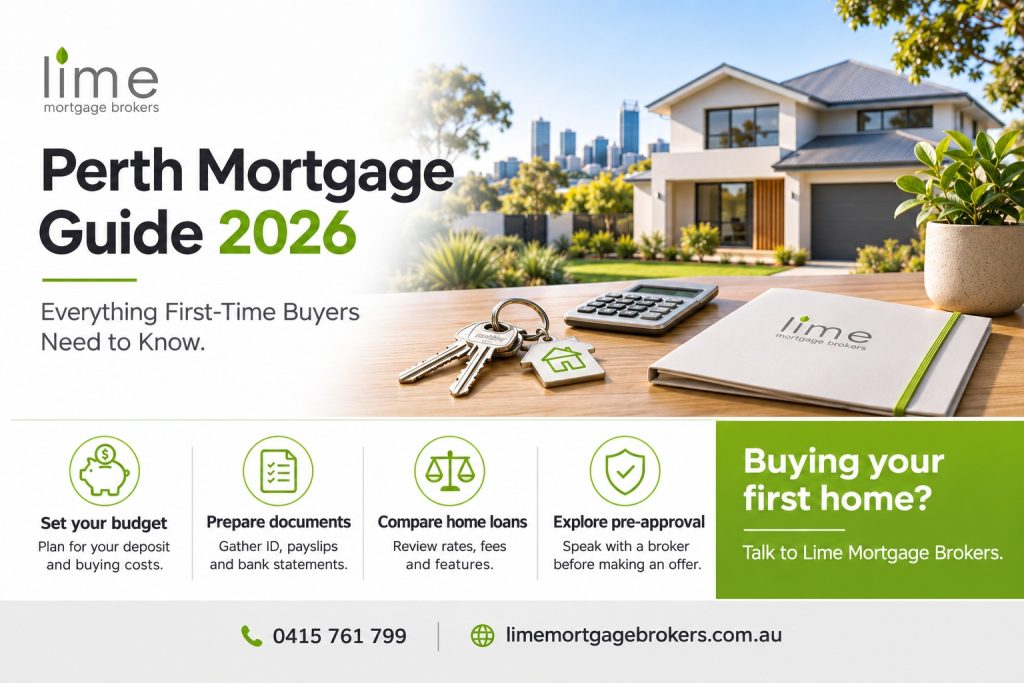
Perth Mortgage Guide 2026: Everything First-Time Buyers Need to Know
Buying your first property can feel overwhelming, especially when lenders have different requirements, interest rates, and approval criteria. This Perth mortgage guide for 2026 helps first-time buyers understand the home loan process, prepare their finances, and explore suitable lending options. Whether you are buying your first property or planning ahead, knowing what lenders look for can help you avoid common mistakes and make more informed decisions.
At Lime Mortgage Brokers, we help buyers across Kinross and Perth understand their options, compare lenders, and prepare home loan applications that match their financial goals. From understanding your borrowing capacity to finding a suitable first home buyer home loan, our team can help you navigate the process with greater confidence.
Table of Contents
Your Perth Mortgage Guide for First-Time Buyers in 2026
Buying a home involves more than finding a property and applying for finance. You need to understand your borrowing capacity, deposit requirements, lender criteria, and ongoing repayment commitments.
This Perth mortgage guide covers the key steps to prepare for a home loan, choose suitable finance options, and understand what to expect when buying your first property in Perth.
With the right preparation and support, first-time buyers can approach the property market with a clearer understanding of their financial options.
Mortgage Brokers: Why First-Time Home Buyers Use Them
Mortgage brokers act as intermediaries between borrowers and lenders. Rather than approaching a single bank, borrowers can access different lending options through one professional.
Many first time buyers want guidance throughout the application process, particularly when they are unfamiliar with lender requirements. A broker can assess borrowing capacity, explain lending criteria, compare loan products, and assist with documentation.
Home loan brokers are particularly useful because every lender assesses income, expenses, savings history, and credit records differently. This means the right lender for one borrower may not necessarily be suitable for another.
A mortgage broker can help match your financial situation with lenders that offer products suited to your circumstances and property goals. They can also explain the differences between loan features, repayment options, and associated fees so you can make a more informed decision.
How to Start Applying for a Mortgage Broker
The first step is arranging a consultation to review your financial position. During this stage, a broker will examine income sources, debts, living expenses, savings, and future goals.
Many buyers ask how to start applying for a mortgage broker. The process is generally straightforward. You provide financial information, discuss your property goals, and receive recommendations on suitable home loans.
Before speaking with a broker, it helps to prepare:
Recent payslips
Bank statements
Identification documents
Details of existing debts
Savings records
Having these documents ready helps the broker provide more accurate borrowing estimates and determine which first home buyer home loan options suit your financial position.
Requirements for Mortgage Broker Applications
Although brokers do not approve loans themselves, they must gather information required by lenders.
Common requirements for mortgage broker assessments include proof of identity, employment verification, income documentation, bank statements, and evidence of genuine savings.
Lenders also review spending habits. Regular account conduct and responsible financial management can improve the strength of an application.
Reducing unnecessary debt before applying can significantly improve borrowing capacity.
Tips Before Applying for Mortgage Approval
One of the most valuable tips before applying for mortgage finance is to avoid major financial changes.
Changing jobs, applying for multiple credit products, or taking on additional debt can affect lending assessments. Lenders generally prefer stability and consistency when reviewing applications.
It is also important to review your credit history before applying. Correcting errors early can prevent delays later in the process.
Saving a larger deposit may provide access to better lending options and reduce lender risk. First time buyers should also consider additional expenses such as stamp duty, legal fees, building inspections, insurance, and moving costs.
Preparing these financial details early can make the application process more manageable and help you understand how much you can realistically afford.
Why Choosing the Right Home Loan Matters
Not all home loans are the same. Interest rates, repayment structures, fees, and loan features vary between lenders.
The best option depends on your financial goals and circumstances. Some borrowers prioritise flexibility, while others focus on minimising repayments.
Perth mortgage brokers often compare dozens of products to identify suitable solutions based on borrowing requirements and long-term plans.
What Type of Mortgage Is Best for First-Time Buyers?
Many borrowers ask what type of mortgage is best for first-time buyers. There is no single answer because every buyer has different financial objectives.
Variable rate loans may provide flexibility and access to additional repayment features. Fixed rate loans can offer certainty by locking repayments for a specified period.
Some buyers choose split loans, which combine fixed and variable portions. This approach allows borrowers to balance repayment certainty with flexibility.
The best loan structure depends on income stability, financial goals, and risk tolerance.
What’s the Best Loan for a First-Time Buyer?
When considering what’s the best loan for a first-time buyer, affordability should be the starting point.
A suitable first-home-buyer loan should comfortably fit within your budget while allowing room for future interest rate changes and unexpected expenses.
Many first-home buyers focus only on interest rates. However, fees, redraw facilities, offset accounts, and repayment flexibility can also influence the overall value of a loan.
An experienced Perth mortgage specialist can explain how these features affect long-term costs and help you compare available lending options.
Mortgage Brokers Perth and Local Property Considerations
The Perth property market continues to attract first-home buyers due to its relative affordability compared with eastern states.
For buyers in Kinross, understanding local market conditions is important. Competition for well-presented homes can be strong, particularly in established family-oriented suburbs.
Mortgage Brokers Perth regularly assist buyers who need finance pre-approval before making offers. Pre-approval can provide greater confidence when negotiating with sellers.
Local buyers should also consider government grants, stamp duty concessions, and eligibility requirements that may apply to first-home purchases.
Being financially prepared before property inspections can provide a significant advantage in competitive markets.
Lime Mortgage Brokers supports clients throughout Kinross and surrounding Perth suburbs by helping them understand lender expectations and finance options.
Contact Lime Mortgage Brokers
If you are planning to buy your first home, refinance an existing loan, or explore your borrowing options, professional mortgage guidance can help you understand the lending process and identify suitable home loan solutions. Getting advice early may help you avoid common mistakes, improve your application, and make more informed financial decisions.
Contact Lime Mortgage Brokers to discuss your home loan goals and receive personalised guidance from experienced mortgage professionals. Whether you are a first-home buyer or looking to secure a better loan structure, taking the first step today may help you move closer to achieving your property goals with greater confidence.
Shawn Swart
t. 0415 761 799
e. shawn@limemortgagebrokers.com.au
w. www.limemortgagebrokers.com.au
Disclaimer
The information contained on the Lime Mortgage Brokers website and in its posts is for general information purposes only. Lime Mortgage Brokers assumes no responsibility for errors or omissions in the contents of this publication. The information we provide may not be relevant for all individual circumstances. You should always seek professional advice before taking action in relation to any of the matters discussed in this publication.
Frequently Asked Questions
Is 2026 a good year for first-time buyers?
Market conditions can change throughout the year. For many buyers, the right time depends more on personal financial readiness than market predictions. Stable employment, sufficient savings, and manageable repayments are usually more important than trying to predict property cycles.
What are the biggest first time home buyer mistakes?
Common mistakes include borrowing beyond comfortable limits, failing to budget for additional property costs, applying with multiple lenders simultaneously, and purchasing without obtaining finance pre-approval.
How much deposit do I need for a home loan?
Deposit requirements vary between lenders. While some loans allow lower deposits, a larger deposit may reduce borrowing costs and improve lending options.
Why should I use home loan brokers instead of going directly to a bank?
Home loan brokers can compare multiple lenders rather than presenting only one lender’s products. This may provide greater choice and potentially better loan suitability.
How long does mortgage approval take?
Approval times vary depending on the lender, application complexity, and documentation provided. Well-prepared applications often progress more efficiently.